
If a pending refund disappeared from your card app, the missing line does not tell you the final outcome.
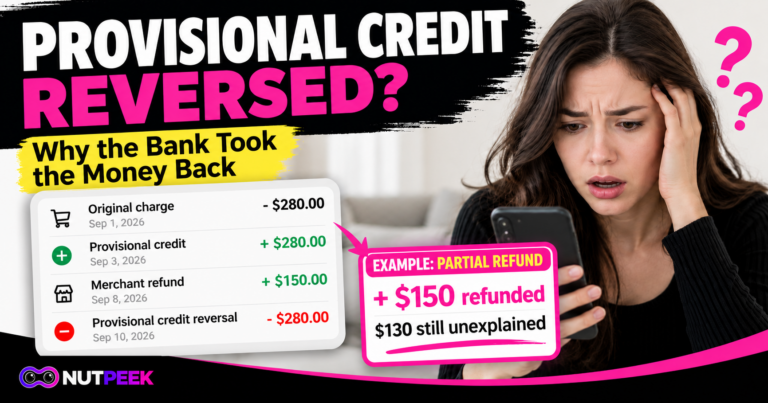
Yesterday: $120 refund — PENDING
Today: Pending refund — GONE
Posted credit: $0
If this is a credit card, the account may still reflect the original $120 charge until a refund credit or reversal is reflected. If it is a debit card, the same symptom can affect cash in your bank account — but the federal credit-card timing rules discussed below do not apply to debit-card refunds.
QUICK ANSWER
A pending refund is not the same thing as a completed credit.
Visa’s current rules require issuers to process credit authorizations so cardholder-facing apps are updated with pending credit information in the same timeframe as purchase transactions. A pending refund can therefore reflect a credit-authorization stage — but the pending line alone is not proof that the final credit has posted.
If the pending refund disappears, check what replaced it:
- A posted credit now appears.
- The original charge disappeared or was reduced.
- Neither happened.
If neither a credit nor a reversal is visible, get the merchant’s refund record and ask your card issuer to check the final credit status.
What a Disappeared Pending Refund Can Mean
The safest way to diagnose this is to look at what your account shows now, not just what disappeared.
1. The refund posted as a credit
Check your posted transactions and statement activity.
If the refund now appears as a posted credit, the pending stage is over. The important number is the final amount credited to the account.
For a credit card, Regulation Z sets two separate timing duties with different trigger events:
- The merchant or other creditor has 7 business days after accepting the return or forgiving the debt to transmit the credit statement through normal card-processing channels.
- The card issuer has 3 business days after receiving that credit statement to credit the account.
The CFPB’s official interpretation also says the issuer does not have to make the refund visibly post within those three business days, as long as the account is credited as of a date within that period.
Those are not a guaranteed “10-business-day refund clock.” They start from different events, and you may not know exactly when the merchant accepted the return or when the issuer received the credit statement.
The rule is also specific to credit-card accounts. Do not use the same federal timeline as a debit-card refund deadline.
2. The original charge was reversed or reduced
Sometimes the money comes back without a separate refund line.
Stripe, for example, says that a refund submitted soon after the original charge can be processed as a reversal. Instead of showing a new refund transaction, the original charge can disappear from the statement and the account balance can adjust.
A partial refund can similarly appear as a lower final charge rather than a separate refund line.
That is a processor example, not a promise that every bank or card network will display refunds this way. The practical check is simple: compare the original charge, the posted balance, and the refund amount.
3. The pending refund disappeared, but nothing replaced it
This is the situation that needs follow-up.
Do not assume the money is gone. Do not assume the refund is still on the way.
A vanished pending line, by itself, does not tell you whether the refund completed, was reversed, failed, or needs to be traced. Start with the merchant.
What to Check — and Who to Call
Step 1: Check the account again
Look for:
- a posted credit for the refund amount
- the original purchase disappearing
- the original purchase being reduced
- a different refund amount
- the refund appearing on another card or replacement credential
Do not rely only on the pending tab. If the credited amount looks different because the purchase involved another currency, see why a foreign-currency refund can come back as less money.
Step 2: Ask the merchant for the refund record
Ask for:
- the date the return was accepted
- the date the refund was submitted
- the exact refund amount
- the last four digits or payment credential used
- a refund receipt or confirmation
- a trace/reference number, if its processor provides one
Some payment processors provide an ARN, STAN, or RRN that can help a bank trace a card refund. Stripe, for example, provides these references for supported transactions.
Not every merchant or processor uses the same reference type, so ask for whatever refund-trace information is available rather than demanding one specific code.
Step 3: Call the card issuer with the merchant’s evidence
Give the issuer:
- original purchase date and amount
- merchant name
- refund amount
- refund date
- merchant confirmation
- any available trace/reference number
Ask whether the credit is:
- posted
- still pending
- reversed
- declined
- or traceable in the issuer’s system
If the original card was replaced, closed, lost, or stolen, mention that too.
Visa’s current rules say merchants should refund the original payment credential where possible. When that credential is unavailable, or a credit authorization is declined, Visa permits specified alternate refund routes.
Step 4: If a credit-card statement should show the refund but does not, the issue can become a billing error
This is where the question changes from “Where did the pending refund go?” to “Why was the credit not reflected on my account?”
Under Regulation Z, a billing error includes the failure to properly credit a payment or other credit issued to a consumer’s account.
For a missing credit, the official interpretation says the 60-day notice period runs from the statement on which the credit should have appeared.
That 60-day path is for credit-card billing errors. It is not a general debit-card refund rule.
If you need to preserve those federal billing-error rights, follow the billing-error instructions on your statement. Regulation Z defines the notice as written, although an issuer can accept an electronic notice if its billing-rights disclosure says that method qualifies.
For a concrete example of the same 60-day billing-error framework, see Rental Car Credit Card Hold Still There After Return?.
What If the Card Was Replaced or Expired?
A replaced card does not automatically mean the refund is lost.
Visa says a merchant should send a refund back to the original payment credential where possible. If that credential is unavailable — for example, because the account is closed, transferred, or reported lost or stolen — or if a credit authorization is declined, Visa rules allow specified alternate paths.
That is why the useful question is not just “Which physical card do I have now?”
Ask the merchant which payment credential or card record the refund was sent to, if they can confirm it, then ask the issuer how that credit is being routed.
Credit Card vs. Debit Card: One Important Difference
The app symptom can look similar on both.
But the Regulation Z timelines in this article — the merchant’s 7-business-day transmission duty and the issuer’s 3-business-day account-credit duty — are credit-card rules.
Do not apply them as a federal refund deadline for a debit-card transaction.
For a debit-card refund, use the merchant’s refund record and the bank’s debit-card processing guidance to trace the transaction.
FAQ
Can a pending refund disappear?
Yes. A pending line is not a permanent transaction record. The useful question is what your account shows after it disappears: a posted credit, a reversed or reduced original charge, or neither.
Does a disappeared pending refund mean the merchant canceled it?
Not by itself. The app display alone is not enough to determine the back-end status. Check the merchant’s refund record and the issuer’s final account activity.
Can a refund come back without a separate refund line?
It can in some processing flows. Stripe, for example, documents reversals where the original charge disappears instead of a separate refund posting. Treat that as one possible processor behavior, not a universal display rule.
What if the merchant says the refund was sent but I still do not see it?
Ask for the refund date, amount, receipt, and any available trace/reference number. Then give that information to the card issuer.
If a credit-card statement fails to show a credit that should have appeared, Regulation Z’s billing-error process may apply.
Amazon says my refund was issued, but it’s not on my card. What now?
First, open Your Returns on Amazon and check the refund status. Then review your refund confirmation email and Your Transactions to confirm the refund date, amount, and destination.
Amazon says credit-card refunds generally take 3–5 business days to process after issuance. Check the refund destination before assuming the money is delayed: a refund sent to your Amazon account balance won’t appear as a card credit.
If Amazon can’t use your original payment method, such as an expired card, Amazon says refunds go to your Amazon account balance.
If the refund was issued to your card and is still missing after the applicable processing period, ask Amazon for the refund confirmation and any available reference information. Then follow Steps 2 and 3 above.
Amazon doesn’t publicly say it provides an ARN, so give your card issuer the refund date and amount and ask them to trace the credit.
Amazon sources: Check Your Refund Status · Refunds.
How long do I have to report a missing credit on a credit card?
Under Regulation Z, a billing-error notice generally must reach the creditor no later than 60 days after the first periodic statement reflecting the alleged error was transmitted.
For a missing credit specifically, the official interpretation says that 60-day period runs from the statement on which the credit should have appeared.
Bottom Line
A pending refund disappearing is not proof the money is gone — and it is not proof the refund is complete.
Check the final account activity first. If there is no posted credit and no reversal of the original charge, get the merchant’s refund record and ask the issuer to trace the credit.
For credit cards, the strongest escalation point is the statement: if a credit that should have appeared is missing, Regulation Z provides a formal billing-error path.
Sources
Visa Core Rules and Visa Product and Service Rules, Apr. 18, 2026 — §§4.1.1.3 and 1.5.4.14
CFPB — Regulation Z §1026.12(e), Prompt notification of returns and crediting of refunds
CFPB — Regulation Z §1026.13, Billing error resolution
Stripe — Where is my customer’s refund?
Stripe — How to trace a refund using reference numbers